
CDW’s UK business grew by over a fifth in Q3, its CEO revealed as the world’s largest VAR raised its full-year outlook amid a boom in AI-fuelled hardware sales.
The Nasdaq-listed giant saw net sales for the three months to 30 September 2026 vault 18% year on year to $6.75bn, with its international business in the UK and Canada growing 26% to $880m.
That’s an acceleration on the 10% and 23% growth in total and international sales it recorded in Q2, respectively.
Hardware did most of the legwork, growing 21% on a global basis, while software net sales swelled 14%, Managed services and professional services returned to modest 2% growth, meanwhile.
The results continue a run of expectation-busting results from the world’s largest VARs and distributors, with the CEO of Logicalis and Westcon parent Datatec recently claiming AI has expanded his company’s addressable market.
On the earnings call, CDW CEO Christine Leahy claimed the “next phase” of AI adoption is underway as demand spreads from large enterprises into the midmarket, small businesses and the public sector.
CDW will take a “greenhouse approach” to recent 600-employee data and AI services acquisition Lovelytics, Leahy stressed.
“[With] the size they are, and the capabilities they have, we’d like to operate them almost separately for a period of time and use CDW as a channel. We don’t want to overwhelm them,” she said.

“Durable” demand
Price inflation left a clear shean on CDW’s numbers, with client device net sales booming 19% even as unit shipments fell.
Despite this, demand is “durable”, Leahy claimed.
Customers are prioritising AI readiness, data growth, network modernisation, cybersecurity, resiliency and hybrid architectures, she said.
All of these things are part of “the preparation stage for utilising AI,” she said.
“At the end of the day, we see the durability of that demand continuing,” Leahy told analysts on the call.
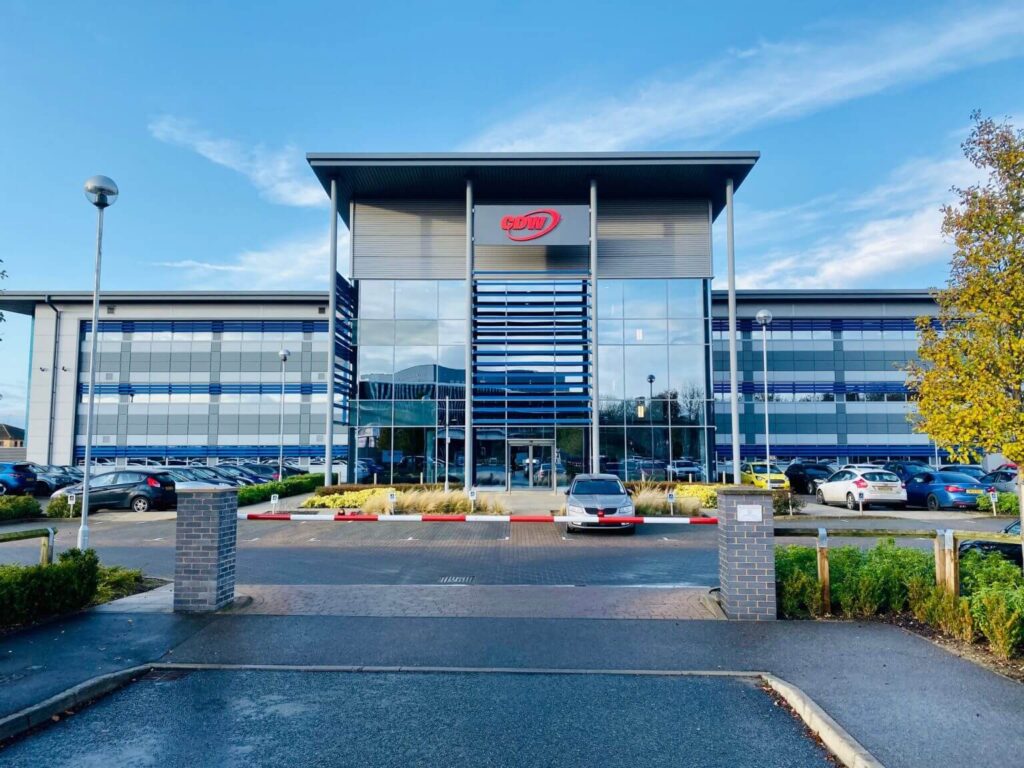
CDW is as a result raising its full-year outlook. Leahy said.
“We now expect the US IT addressable market to grow at a high single-digit rate in 2026 on a customer spend basis, and we see 300 to 400 basis points of CDW outperformance compared to the market,” she said.
Despite not splitting out exact numbers, CDW revealed that both its UK and Canadian arms grew by “more than” 20% during the quarter.
CDW’s Q3 earnings come after LSE-listed peer Computacenter last month yet again raised its full-year outlook amid insatiable demand among hyperscalers for IT infrastructure. Softcat also recently topped expectations for its full year.
CDW’s shares leapt around 20% on the news, propelling its market value to above $21.2bn.