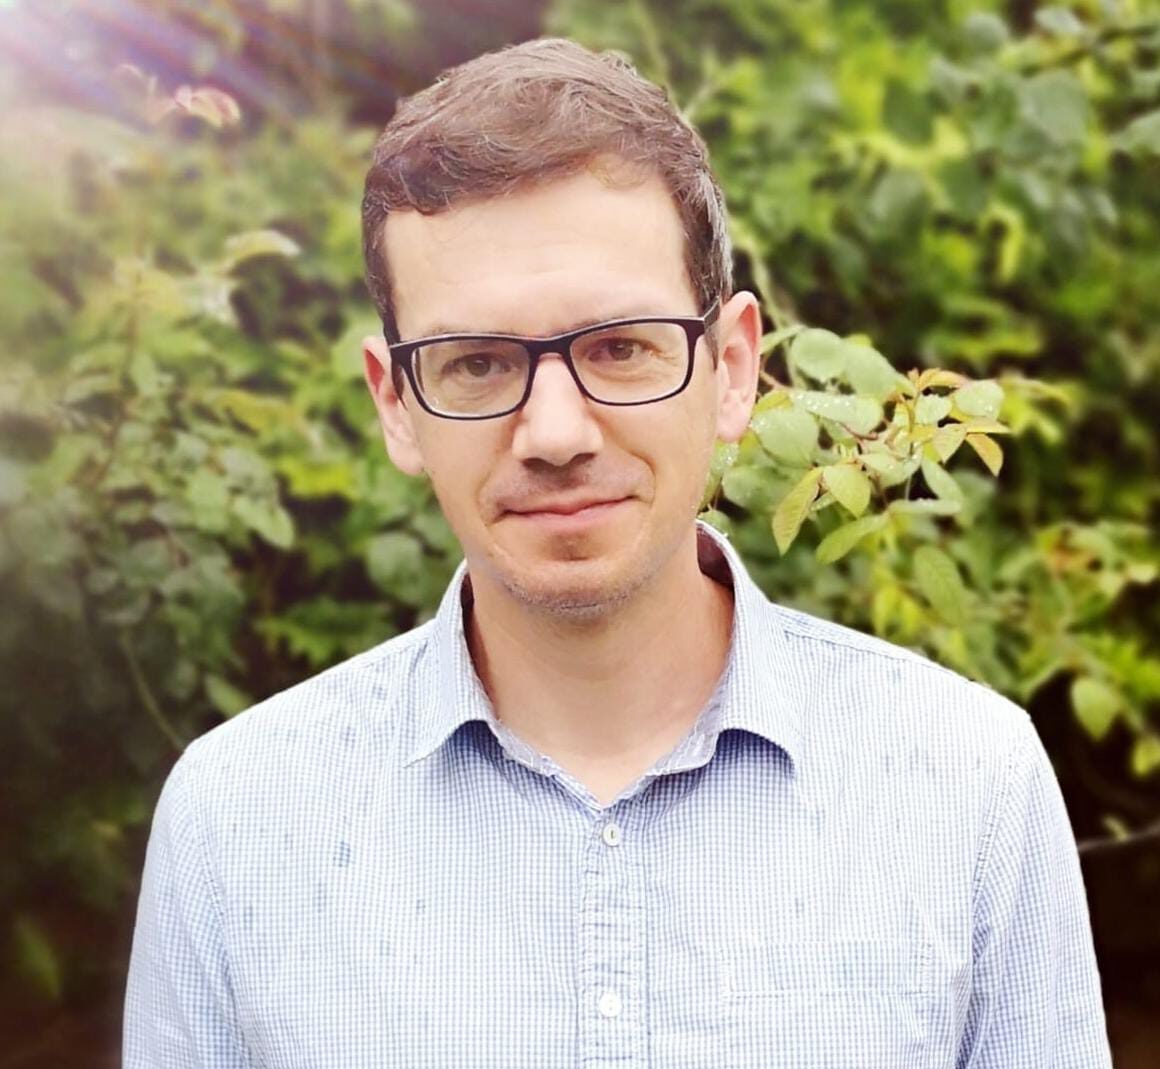
Softcat ran the rule over more than 100 US firms over “five or six years”, but only held serious talks with $1bn conquest GDT, its CEO revealed.
The LSE-listed VAR tonight announced it has signed an agreement to acquire Texas-based GDT, a “multi-vendor IT solutions provider” we understand turns over more than $1bn.
It will fund the deal, which is for an enterprise value of $1.05bn (£785m), partly through a planned £350m equity placing.
The news comes 11 months after Softcat CEO Graham Charlton laid out his ground rules for a possible US acquisition.


Talking to IT Channel Oxygen tonight, Charlton said the timing of the deal was a function of it finding the right target, rather than Softcat being ready.
Charlton first met GDT CEO Shawn O’Grady four years ago, when he took the top job at the Dallas-based networking, data centre, AI infrastructure and cybersecurity specialist, which counts Cisco, NetApp and NVIDIA among its key vendors.
“This is the only target we’ve talked to in a very serious way,” he said.
“We’ve probably done pretty significant work on about ten. We probably screened and looked at more than 100.

“We instigated this proactively – this wasn’t part of a competitive process,” Charlton said, adding that previous owner HIG “wasn’t ready to sell this year”.
“The thing that convinced HIG to talk to us – they wanted to sell at some point further down the line – was that their team’s excitement to join forces with Softcat became pretty overwhelming,” he said.
Why has Softcat gone so large?
Computacenter has built a circa $10bn North American business on the back of five sizeable acquisitions over the course of the last eight years – including two in 2026.
Softcat’s decision to plump for a single, much larger target was a deliberate ploy, Charlton revealed.
“What we don’t want is to distract our UK and Ireland business from the pathway it’s already on,” he explained.
“We were always interested in investing in something with a scale that we could put emphasis and investment behind and bring our know-how to, but which wouldn’t drag our key management leadership out of our business and be a distraction.”

The deal, which is set to close in calendar Q1 of 2027, also gives Softcat’s existing US staff a “huge opportunity”, Charlton claimed.
“It puts into their hands the exact sort of capability they need to execute for our UK customers, so this is terrific news for them,” he said.
The GDT name will stay “for now”, Charlton said, emphasising that both businesses will “continue to run along the tracks we’re already on”.
“Over time we’ll find ways to add value between and on top of the way those operations already work,” he added.
“We’re doing this from a position of strength”
Softcat also tonight raised its full-year underlying profit growth guidance from mid to high teens after saying it “continued to trade well” in its final quarter (ending 31 July).
“Our business is about 40% bigger now than it was two years ago. So we’re doing this from a position of strength,” Charlton said.
Serving 700 upper-mid market and enterprise customers, GDT is set to generate gross profit of around $240m and EBITDA of around $80m this calendar year.
When it comes to serving the needs of large, complex customers, Softcat is now in the “top echelon of capability for that on a global basis”, Charlton claimed.
In the full interview, published below, Charlton opens up fully on the rationale for timing and size of the deal.
What did he say? Read more on the following page…