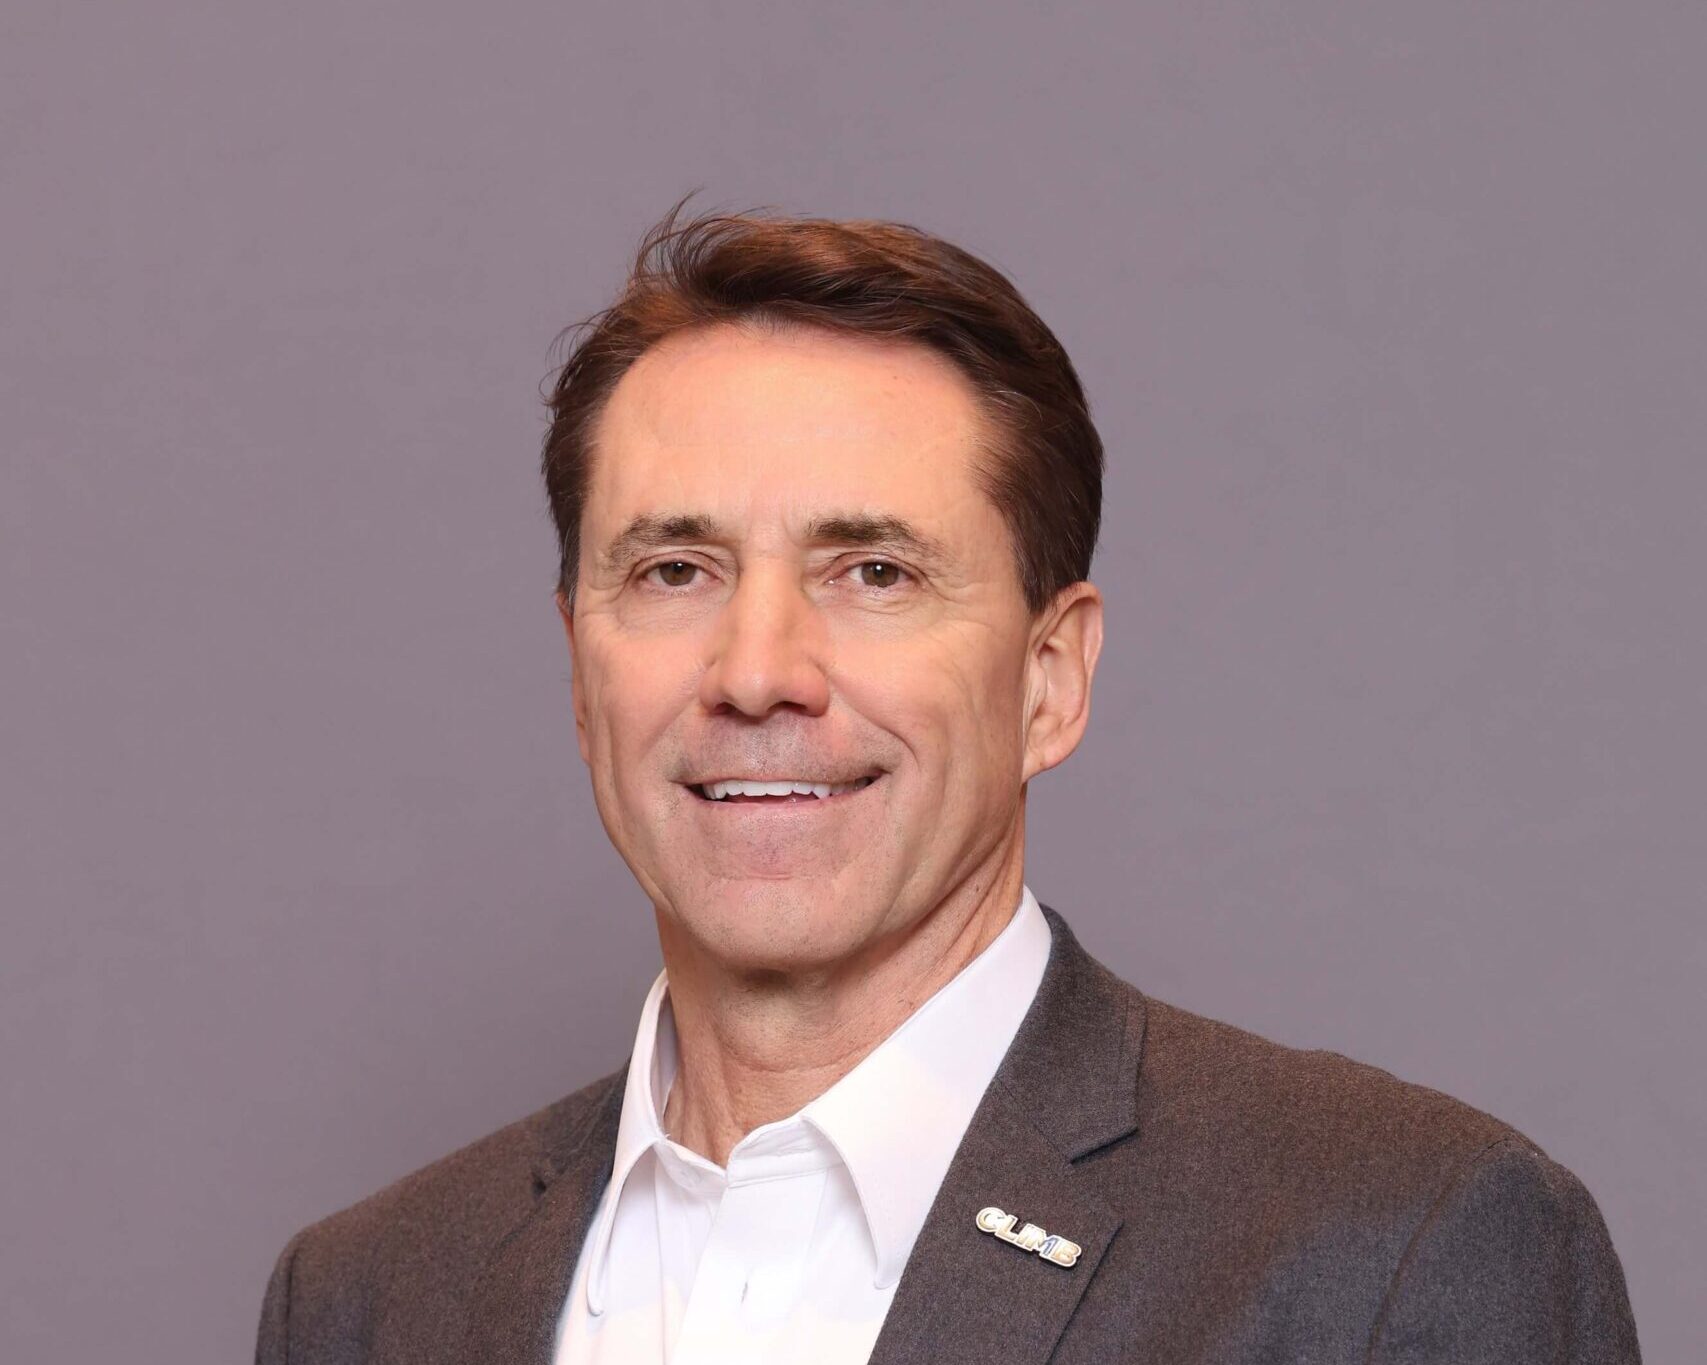
Climb plans to acquire “two to three” European distributors in both 2027 and 2028, its CEO revealed as he spoke of the importance of building a $1bn business here.
The Nasdaq-listed distributor, which counts VAST, Solarwinds, ManageEngine and Quest among its vendor allies, last week made its second European conquest of 2026 in the shape of French VAD NeoVAD.
Its European business currently generates around a fifth of its top line, which rose by 40% to $706.3m in its latest quarter.
It achieves double the margins of its US business, CEO Dale Foster told IT Channel Oxygen.
“If we can get our European operations into that billion-dollar range, that will really have an impact on our Wall Street numbers,” he said.
“We’re going to acquire two to three [European distributors] next year, and two to three the year after that.”
“They’re starving for vendors”
NeoVAD marks Climb’s second European M&A move of the year following its February swoop on interworks.cloud.
The Boulogne-Billancourt-based VAD turns over “just over” €30m, putting it in Foster’s €30m-€100m-revenue hunting zone.

The deal comes two-and-a-half years after Climb hired Kamel Kerbib as its France Country Manager, a move Foster said had enabled it to obtain the “lay of the land” there.
“We were transacting in France out of our Netherlands office and got to know some of the distributors – we had four of five on our target list,” Foster said.
“France was not as important to me as Germany, just by GDP and also because we think of it as more of a closed market – but we met with [NeoVAD founder] Jérôme [Boulon] and were like, ‘wow, this culture fits us’.”
Foster characterised the €16m deal as “one of the smoothest transactions we’ve had”.
“We can have the biggest impact on that company versus some of the other ones we’ve acquired, because they’re starving for vendors,” he said.
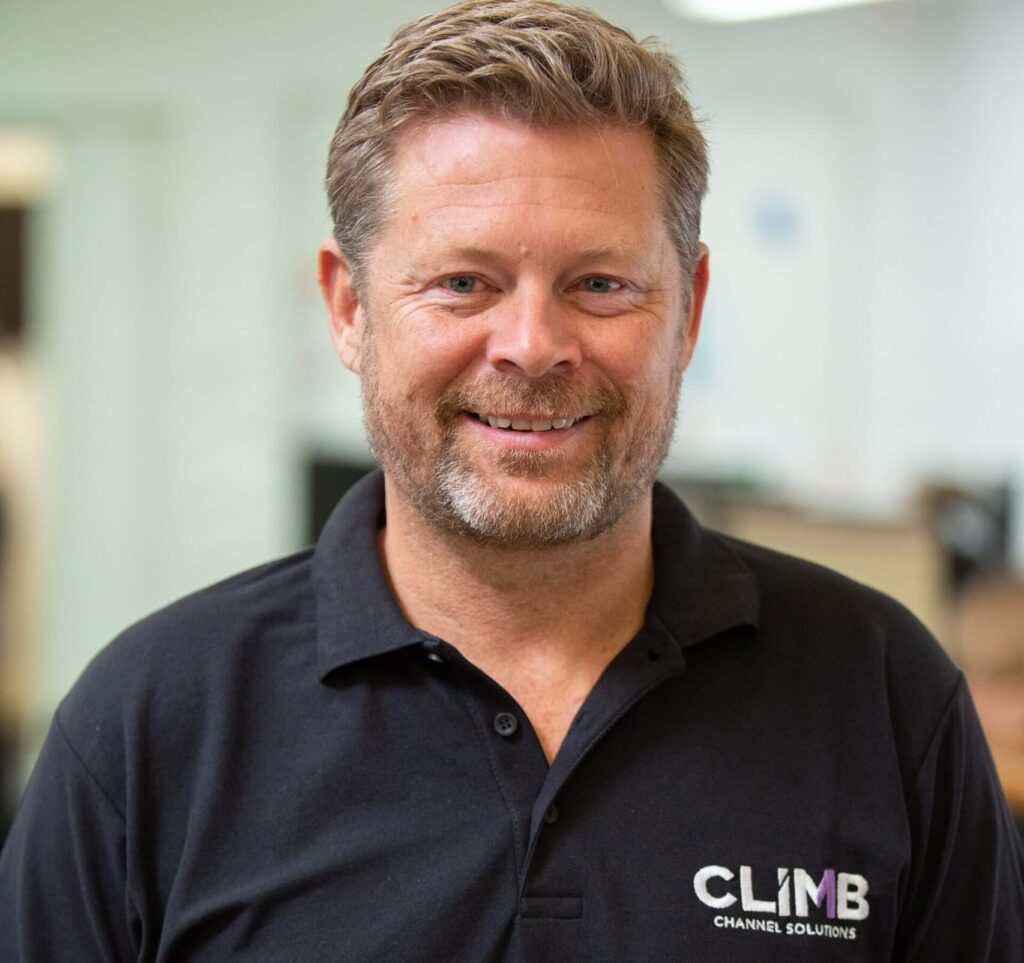
“Within a week, we’ve had seven or eight different vendors saying ‘that’s the market we want to get in’,” CRO Gerard Brophy added.
“I think a lot of American vendors struggle with employing in France, and struggle with the language itself. So I think one of the growths with NeoVAD will definitely be introducing new vendor lines to them.”
“They’re not getting the feeding from other distributors”
Despite a full quarter’s contribution from February acquisition of interworks.cloud, most of Climb’s 40% gross sales growth during its Q3 ended 30 September was organic, Foster said.
Some 19 of Climb’s top 20 vendors generated sequential growth during the quarter, up from 18 in Q2, which Foster attributed partly to the distributor sitting in a “great space”.
“70% of our vendor lines are in cybersecurity, which if you listen to Canalys and some of the other analysts is a 13-15% growth market – we’re taking advantage of that,” he said.
“Some of it is share shift, because they’re just not getting the care and feeding from the other distributors.
“If I look at how many vendors generate more than $25m, it used to be the top 15. Now it’s the top 25.”
Foster picked out the “big three” of TD Synnex, Ingram, Arrow as well as Exclusive Networks and Infinigate as his main European competition.
“We’re a better choice for a higher-touch experience than our competitors,” he said.
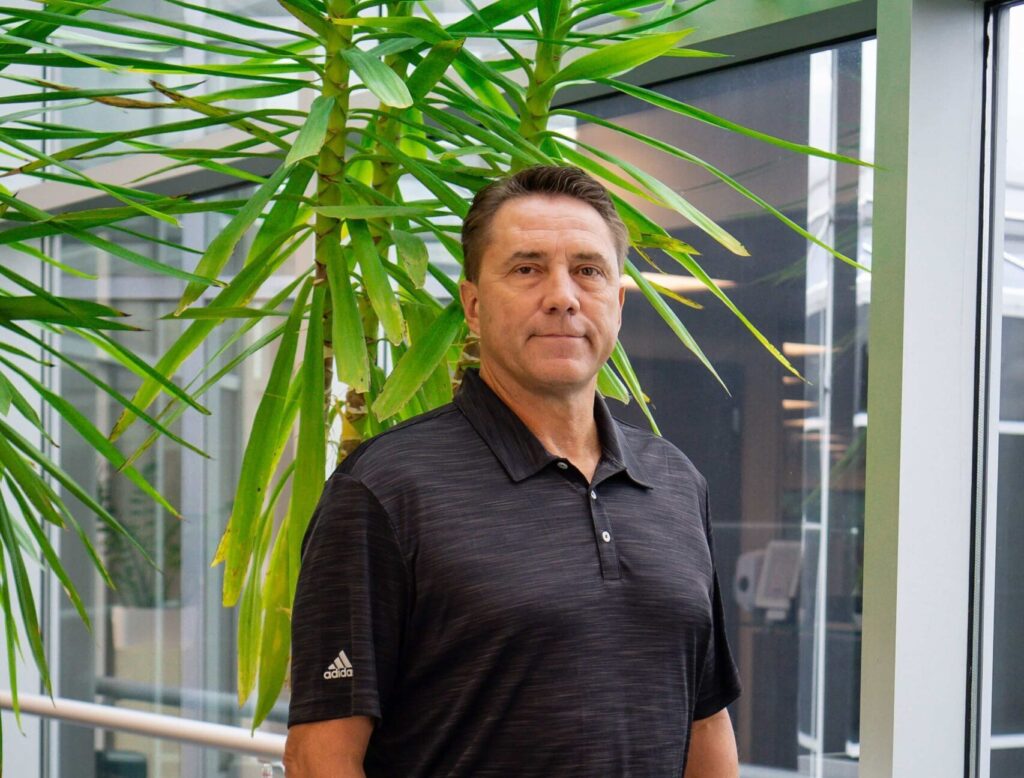
Does Foster wish software-focused Climb possessed a bigger hardware business as a new, AI-driven “technology super cycle” gathers pace?
“My history is on the hardware, datacentre side… but software is so much easier – you have to go and sell a piece of hardware every month, every quarter,” he responded.
“I don’t think that lasts long – I think people are pre-buying a lot.”
Foster contrasted Climb’s vendor strategy with that of fast-growing UK-headquartered QBS Software, which has over 12,000 vendor partners on its delivery platform.
“We’re not trying to build a broadline distributor,” he said.
“NeoVAD have got less than 15 lines, and in North America, we’re trying to trim our number from 70 to 50. We want to be that speciality distributor that goes a little wider and deeper in our customer base.”
When it comes to European M&A, Climb could replicate its early-decade deals for Sigma/Grey Matter, Spinnakar and DataSolutions by acquiring again in the UK, Foster stressed.
“There are still some really good targets in the UK,” he said.
“We’ve looked at a couple in the Nordics, but haven’t pulled the trigger on them. But it’s going to be in Europe and adjacent.”
Doug Woodburn is editor of IT Channel Oxygen